 AppRank

Screenshots




Beschreibung
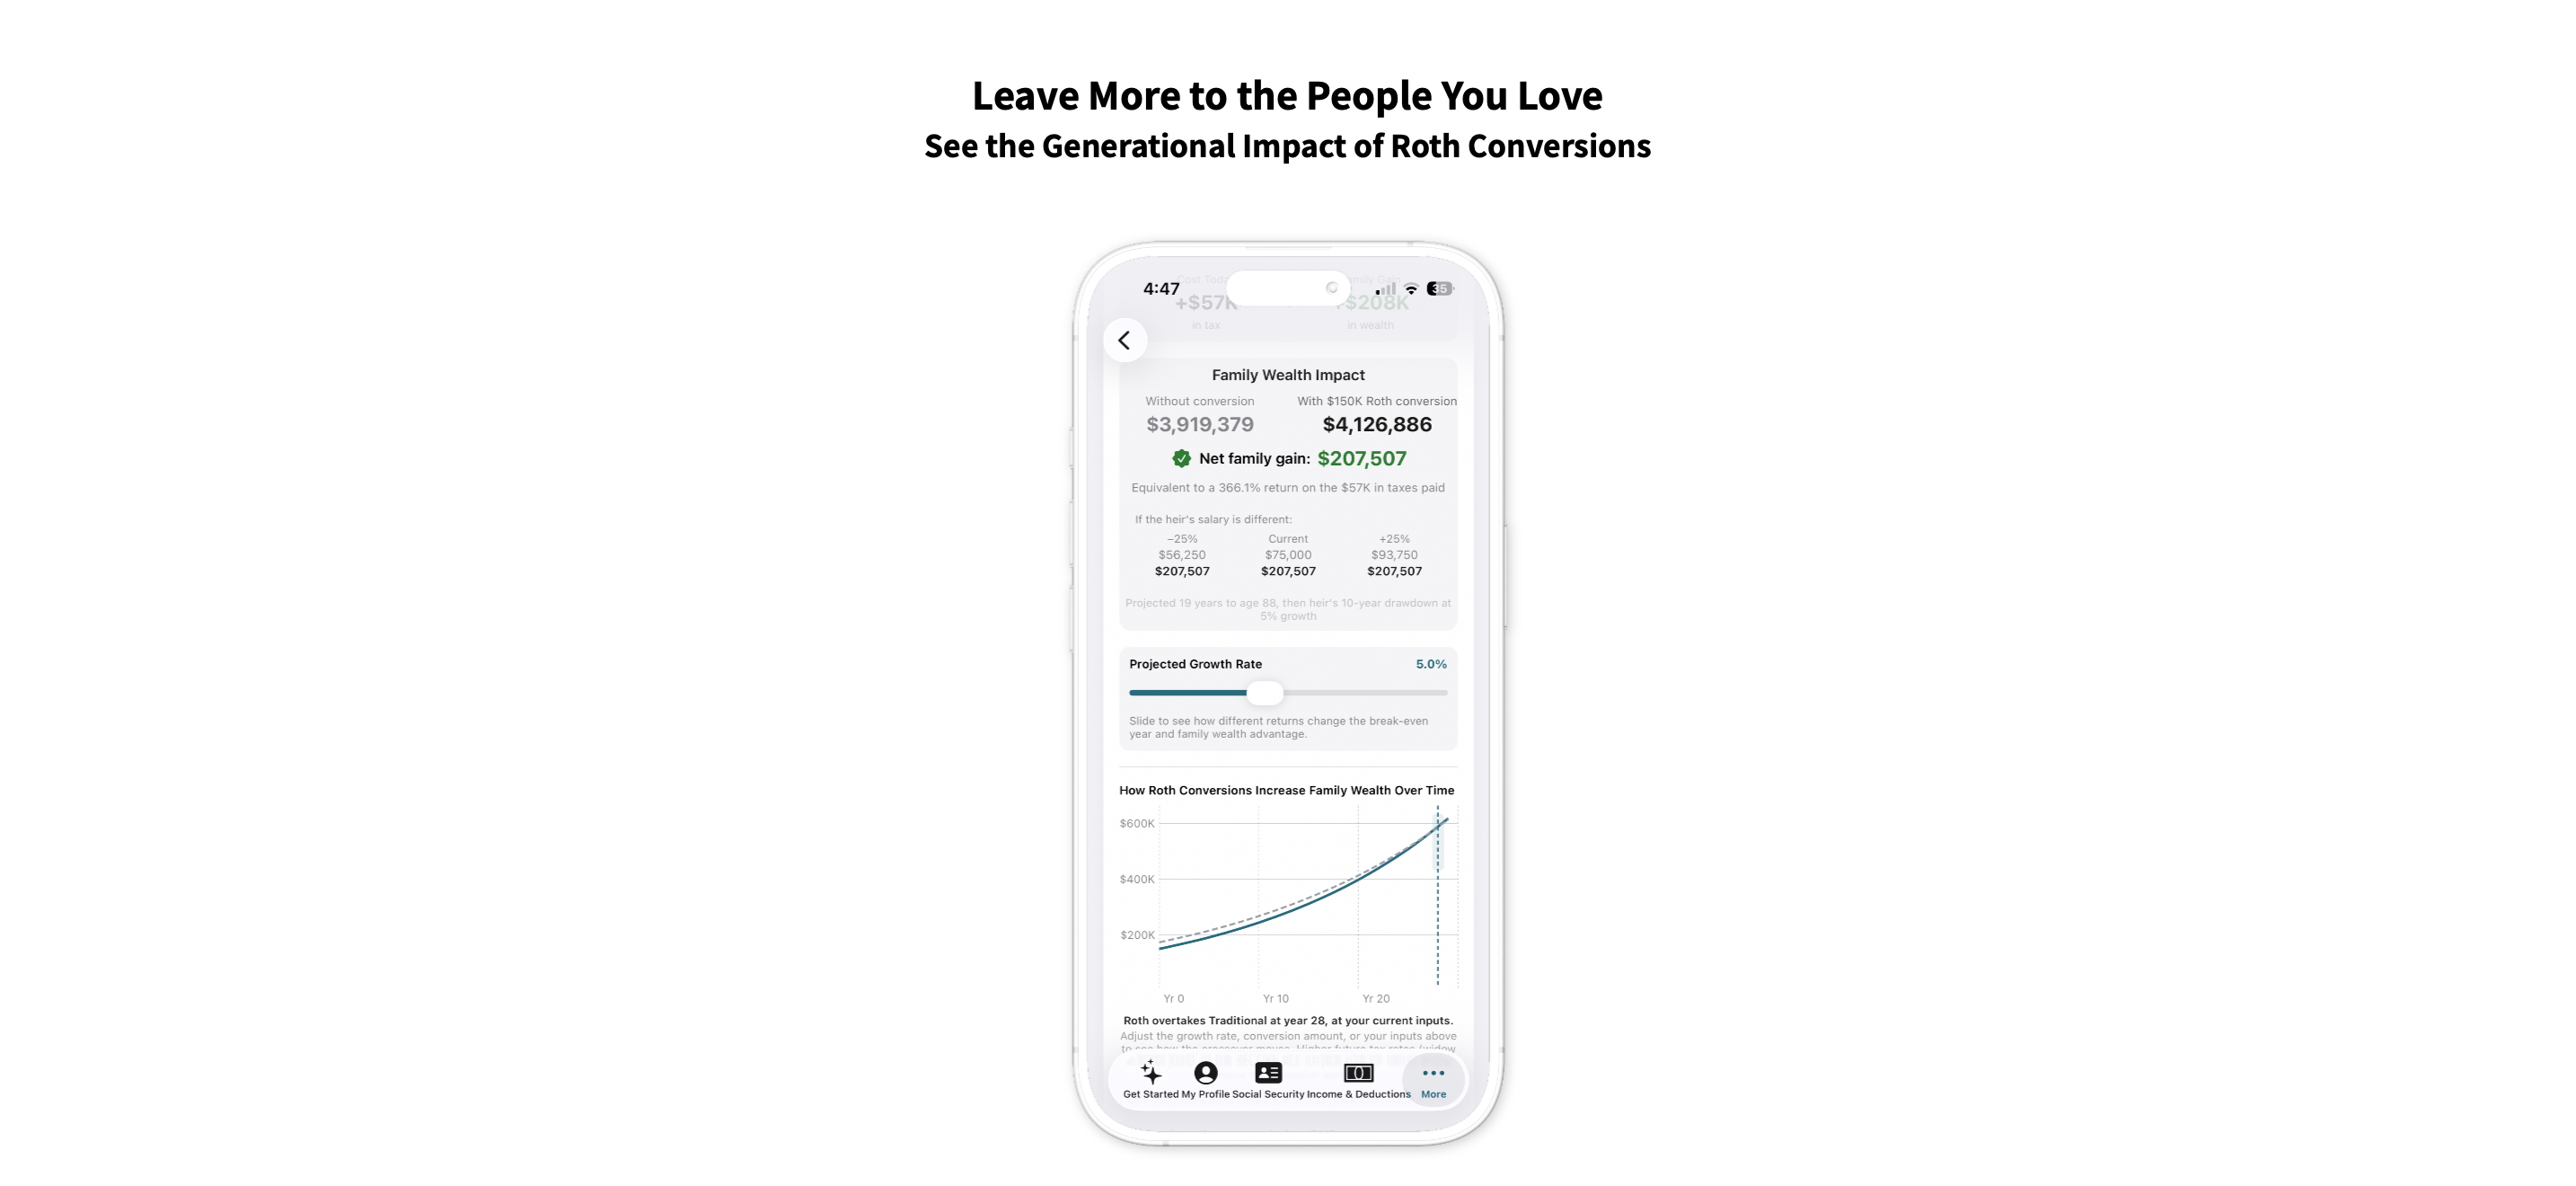
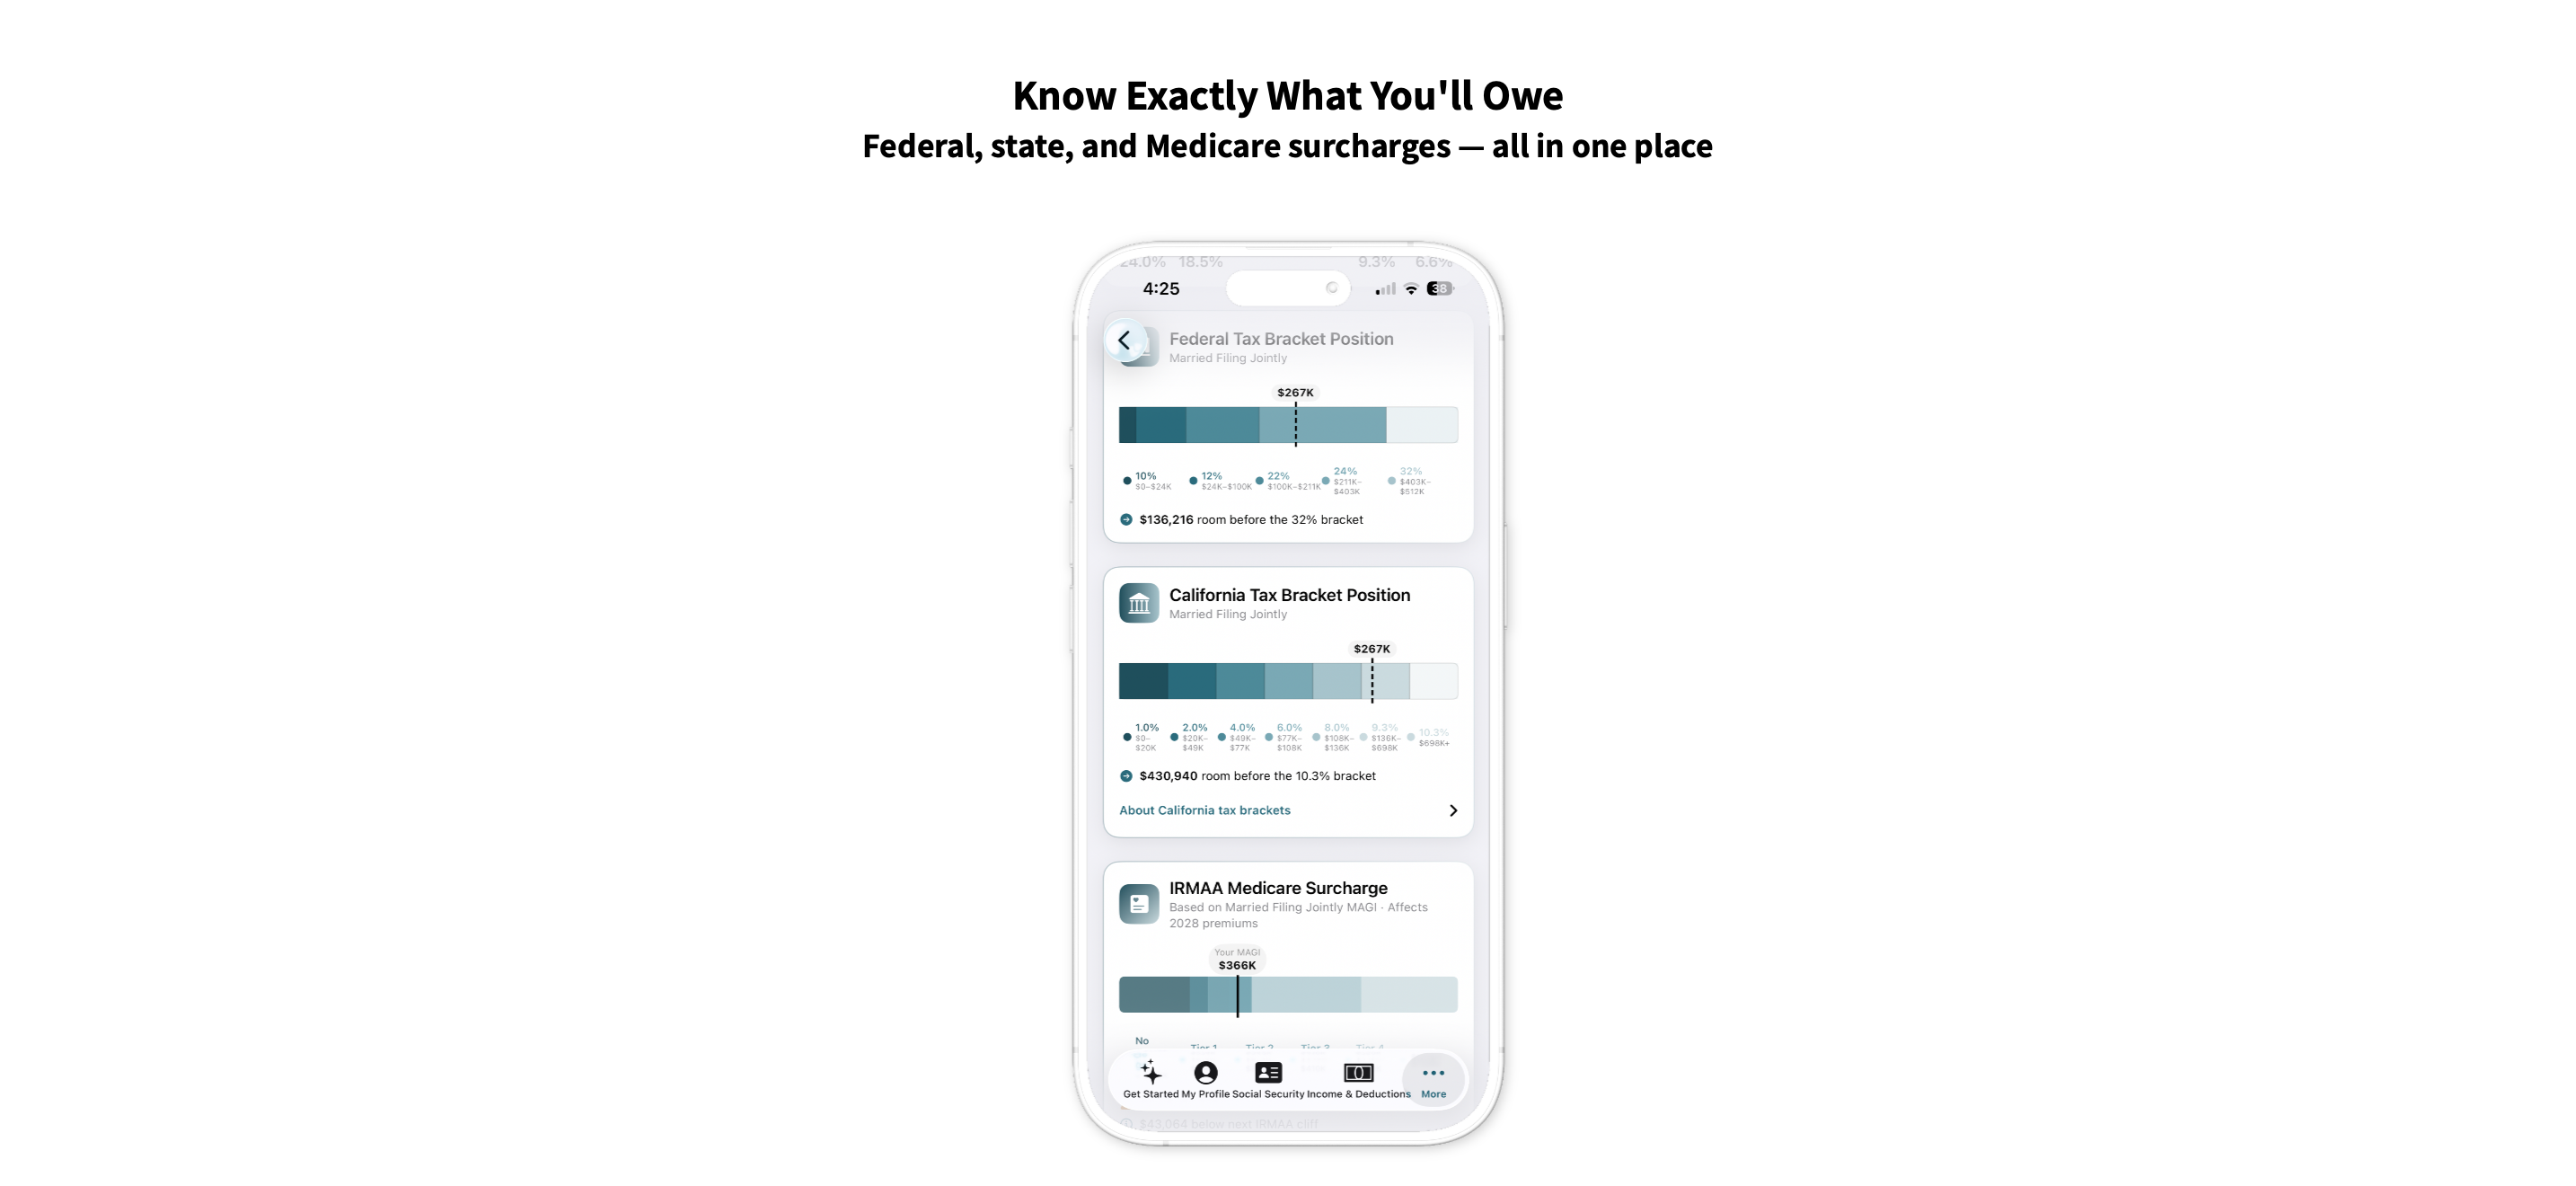
Plan your retirement taxes like a pro — this year, next year, and across retirement. RetireSmartIRA helps you model the tax decisions usually scattered across spreadsheets, IRS worksheets, and CPA meetings: Roth conversions, Social Security timing, RMDs, IRMAA, the ACA cliff, and more. It's built for the financially engaged: people who want to understand their numbers, not just be told what to do. No spreadsheets, no black boxes: every dollar traces back to the input that produced it. ANSWER THE QUESTIONS THAT ACTUALLY MATTER • What will I owe this year? Estimate federal tax, state tax, NIIT, IRMAA, ACA effects, and withholding needs before tax time. • How much should I convert to Roth this year, and over time? Build a multi-year conversion ladder instead of guessing. • When should my spouse and I claim Social Security? Compare claiming strategies across both lifetimes and survivor outcomes. • Which year should I make a major charitable gift? Test gift timing against conversions and your projected tax bill. • What does my family actually keep? Compare your lifetime taxes with what heirs may owe on inherited IRA assets. MULTI-YEAR TAX PLAN The Multi-Year Plan builds a Roth conversion strategy across your retirement horizon, then lets you choose how to convert: minimize lifetime tax, fill to a target tax bracket, or stay under a Medicare IRMAA tier. Compare the approaches side by side. Choose how each year's conversion tax is paid, and enter wages and pension income year by year for either spouse. See the projected impact on lifetime taxes, ending IRA and Roth balances, future RMDs, IRMAA exposure, and inherited-account taxes. Model charitable giving (QCDs and cash gifts), adjust any year, review the assumptions, and export a CPA-ready briefing. SCENARIO BUILDER: PLAN IN REAL TIME Test Roth conversions, withdrawals, QCDs, charitable gifts, withholding, and Social Security changes before you act. One screen shows federal tax (2026 brackets), state tax (all 50 states + DC), NIIT, IRMAA surcharges, ACA effects, standard vs. itemized with SALT cap math, and taxable brokerage income. See the cost of each converted dollar: every bracket, state step, and surcharge named where it begins. QUARTERLY ESTIMATED TAXES Record what you have paid: a payment ledger with dates and federal and state amounts, measured against each IRS due date and your safe-harbor target. Withholding counts across the year the way the IRS credits it, and your coverage prints in the report. RETIREMENT DRAWDOWN Project how your IRA and 401(k) balances spend down over 40 years: RMDs only, a target spending level, or a withdrawal rate. See when your income reaches the first Medicare IRMAA tier, in future or today's dollars. SOCIAL SECURITY COUPLES PLANNER Compare claiming at 62 vs. FRA vs. 70 for both spouses, with lifetime benefits and survivor protection side by side. RMD CALCULATOR FOR YOUR IRA AND INHERITED IRAs Most calculators get inherited IRAs wrong. RetireSmartIRA handles RMDs at 73 (or 75 under SECURE 2.0), spousal inherited IRAs, the 10-year rule, and stretch options for eligible beneficiaries. WHO IT'S FOR • Anyone doing this year's retirement tax planning: conversions, withdrawals, charitable gifts, withholding • Pre-retirees mapping out a multi-year Roth conversion strategy • Retirees managing RMDs, IRMAA, and the ACA cliff • Anyone with a government pension, 457 or 403(b) whose state taxes it differently • Federal/military households (FERS, military retirement, VA Disability) ALWAYS CURRENT Every IRS limit, HHS poverty guideline, ACA threshold, and Medicare bracket reflects 2026 values. State tax data is verified against each state's own published forms, and every state shows the date it was last checked and the sources behind it. PRIVATE BY DESIGN Your financial data never leaves your device: no cloud accounts, no data harvesting, no ads, no subscriptions. BUILT FOR APPLE Native iPhone, iPad, and Mac app. Free on all three.
Neuigkeiten
Version 2.7.4 · 30.9.20262.7.4: Accuracy Improvements Multi-Year Plan - Each future year now uses that year's projected federal tax law. Brackets, the standard deduction and other amounts the tax code indexes rise each year the way current law sets out, as do IRMAA thresholds and the ACA poverty line. Figures already published, such as the 2027 ACA table and the Medicare Trustees' premium projections through 2035, are used as published. State tax rules are held at 2026 levels, and the plan says so - Two new Advanced assumptions: how far chained CPI runs below your inflation rate, and how fast Part B premiums grow after 2035 - The plan search now compares a wider range of conversion schedules, including steady conversions spread over several years, every time it runs. It never returns a plan that scores worse than converting nothing, and conversions stay outside your IRMAA safety buffer - The plan's goal is now named Lowest lifetime tax cost. It combines modeled taxes over the plan with deferred tax remaining in traditional IRA assets at the end, and values future amounts using your assumed investment return - The approach comparison now leads with that lifetime tax cost, the measure the plan is chosen on. Present-value tax paid is shown as a separate, labelled row - Every figure in the comparison now names its basis, and each column shows whether its plan funds all spending and tax - Years where planned spending cannot be paid are now shown as unfunded, and when no plan can fund every year the screen says "No fully funded plan found." - Tax is now paid in full each year under the tax-funding method you chose, including the tax on gains from selling investments to pay it - New Survivor stress test for couples: if the higher-earning spouse dies at the start of the plan and the survivor files single, it shows how lifetime tax cost would change, higher or lower. The survivor receives the larger Social Security benefit; other planning assumptions remain unchanged - With legacy planning on, the owner and heirs trade-off, the plan on screen, the comparison and the CPA briefing now all describe the same plan for your chosen weighting - The income and tax thresholds chart now shows each year's projected thresholds - Modeled conversions are described as "modeled" throughout - Required minimum distribution cash not needed for spending now pays that year's tax first, before investments are sold or more is withdrawn from an IRA CPA briefing - Leads with lifetime tax cost, with present-value figures shown at your stated discount rate - The year-by-year table adds ACA and NIIT and a total tax column that sums to lifetime tax paid - Adds the Survivor stress test and states the present-value rate used for reporting Scenarios and Quarterly Tax - Mark as taken now asks for the date each withdrawal was made and lists every one you record. Add a later withdrawal to the amount, then mark the added amount as taken on its own date - The Roth conversion card now takes state withholding as well as federal, and Quarterly Tax and the printed report count it toward your state tax - The printed report's State Average Rate and State Marginal Rate are now figured on your state taxable income - On Mac, printed reports keep each table row whole across page breaks
Informationen
- Anbieter
- Alamo Ventures Group LLC
- Kategorie
- Finance
- Version
- 2.7.4
- Erfordert
- iOS 18.6+
- Größe
- 10.2 MB
- Altersfreigabe
- 4+